Proposition 19: Can Your Property Tax Base Move With You?
Home Selling
Home Selling
There is a conversation Dale Warfel and Helen Gardin have several times a year.
It usually starts with a longtime South Bay homeowner who has been in the same house since the 1980s or 1990s.
The house no longer fits. Maybe the stairs have become inconvenient. Maybe the yard is more work than they want. Maybe the kids have been gone for years and there are rooms nobody uses anymore.
They would like to move closer to family, into a single-story home, somewhere quieter, or simply into something that fits this stage of life better.
Then comes the sentence that often ends the conversation:
“We can’t move. Our property taxes would triple.”
The concern is understandable. But the conclusion may be wrong.
Since April 2021, Proposition 19 has allowed qualifying California homeowners age 55 or older to transfer the taxable value of their primary residence to another primary residence anywhere in California.
For longtime homeowners with a low assessed value, that can completely change the math of moving.
California property taxes are generally based on an assessed value that begins with the property's value when it changes ownership and then increases within limits established under Proposition 13.
That starting point is called the base year value.
Over time, allowable annual adjustments are applied to it. The resulting number is commonly called the factored base year value.
That is why two similar homes on the same street can have dramatically different property tax bills.
A homeowner who bought in 1991 may still have an assessed value tied largely to that purchase, adjusted over the years. A neighbor who bought a similar home recently may have an assessed value much closer to today's market value.
Same street. Similar homes. Very different property taxes.
For many longtime Silicon Valley homeowners, that difference is one of the biggest reasons moving feels financially unattractive.
Before Proposition 19, California's property-tax transfer rules for homeowners age 55 and older were much more restrictive.
Proposition 19 created a broader statewide system beginning April 1, 2021.
A qualifying homeowner age 55 or older may use the Proposition 19 base year value transfer benefit up to three times.
The replacement primary residence can be located in any California county.
That means a homeowner can potentially move from Santa Clara County to Sacramento, Sonoma, San Diego, Palm Springs, the Sierra foothills, or elsewhere in California and still qualify.
This is one of the most important changes under Proposition 19.
A replacement home does not have to cost less than the home you sell.
If the replacement residence falls within the applicable “equal or lesser value” threshold, the original factored base year value can generally transfer without an additional amount being added.
Those thresholds depend on timing:
If the replacement home exceeds the applicable threshold, you do not lose the entire benefit.
Instead, the amount above that threshold is added to the factored base year value being transferred.
That distinction is important.
A more expensive replacement home may still receive substantial Proposition 19 property-tax relief.
The replacement residence must be purchased or newly constructed within two years of the sale of the original residence.
That can be either:
before the sale, or
after the sale.
So Proposition 19 does not require you to sell first.
But the timing can affect both the calculation and the logistics of the move, which is why it makes sense to understand the rules before putting either transaction in motion.
The qualifying claimant must be at least 55 years old when the original primary residence is sold.
If a married couple owns the property and only one spouse is 55 or older, the younger spouse does not automatically prevent the transfer.
However, the spouse who meets the age requirement must also satisfy the applicable ownership and eligibility requirements.
That is one of several reasons individual situations should be confirmed with the county assessor.
The benefit applies to qualifying principal residences.
It is not a general property-tax transfer for a vacation home, second home, or investment property.
The claimant must also meet the applicable ownership and occupancy requirements for both the original and replacement residences.
The Proposition 19 transfer is not automatic.
For homeowners qualifying based on age, the claim is made using Form BOE-19-B, filed with the assessor in the county where the replacement property is located.
The normal filing period is within three years of purchasing the replacement residence or completing its new construction.
A late claim may still receive relief, but generally only beginning with the year in which the claim is filed rather than retroactively to the original qualifying date.
For that reason, this is not something to leave sitting in a closing file and assume will take care of itself.
Consider the homeowner who bought a South Bay house 30 years ago.
The home may now be worth several times what they paid for it, while its taxable value has increased much more slowly.
They may assume that selling means giving up that advantage and being reassessed entirely at today's market value on the next home.
So they stay.
They stay in the house with stairs they would rather not climb.
They keep maintaining a yard they no longer enjoy.
They remain farther from children or grandchildren than they would like.
Or they simply continue living in a home that stopped fitting their life years ago.
Proposition 19 does not automatically make moving the right decision.
But it may mean the decision deserves a second look.
The better question is not:
“Will my property taxes go up if I move?”
The better question is:
“What would my property taxes actually look like under Proposition 19?”
That is a number worth understanding before deciding the move is impossible.
Our role is not to calculate your property taxes or give tax advice.
That belongs with the county assessor and your tax professional.
Our role is to help you understand the real estate side of the decision.
That means working through questions such as:
What might your current home realistically sell for?
What might you net after the sale?
What type of replacement home are you considering?
Would selling first or buying first make more sense?
How does the Proposition 19 two-year window fit into a realistic moving plan?
And, most importantly, does the move still make sense once you put real numbers around it?
We help longtime Silicon Valley homeowners turn what can feel like a vague financial concern into a concrete decision.
A qualifying homeowner age 55 or older may generally use the Proposition 19 base year value transfer benefit up to three times.
Yes.
The replacement primary residence may be located anywhere in California.
You may still qualify.
Depending on when the replacement is purchased or constructed, the applicable equal-or-lesser-value threshold can be 100%, 105%, or 110% of the original home's market value.
If the replacement exceeds the applicable threshold, the excess amount is generally added to the factored base year value being transferred.
Yes.
The replacement may be purchased or newly constructed within two years before or after the sale of the original residence, assuming all other requirements are met.
Not necessarily.
If one spouse meets the age requirement and otherwise qualifies as the claimant, a younger spouse does not automatically disqualify the transfer.
Ownership details matter, so confirm the specific situation with the assessor.
Yes.
For a homeowner qualifying based on age, the claim is generally made using Form BOE-19-B with the assessor in the county where the replacement residence is located.
If you bought your home decades ago, it is easy to assume that moving means giving up the property-tax advantage you have accumulated over the years.
That assumption may be costing you options.
If you are 55 or older and have been telling yourself that moving is simply too expensive because of property taxes, find out what the current rules actually mean for you before making that decision.
You may still decide to stay.
But it should be because staying is the right choice — not because of a tax rule that no longer works the way you thought it did.
This article provides general information about Proposition 19 and is not tax or legal advice. Eligibility and calculations depend on individual facts. Confirm your situation with the county assessor where the replacement residence will be located and with your own tax or legal advisor.
If you are considering a move in or out of Silicon Valley and want to understand the real estate numbers before making a decision, call or text Dale Warfel and Helen Gardin at 408-647-7211.
Related reading:
Posted by Dale Warfel and Helen Gardin, The Warfel Gardin Group at Pulse Real Estate
Stay up to date on the latest real estate trends.
Home Buying
Neighborhoods, homes, schools, commute considerations, and what buyers should know before choosing Palo Alto
Home Buying
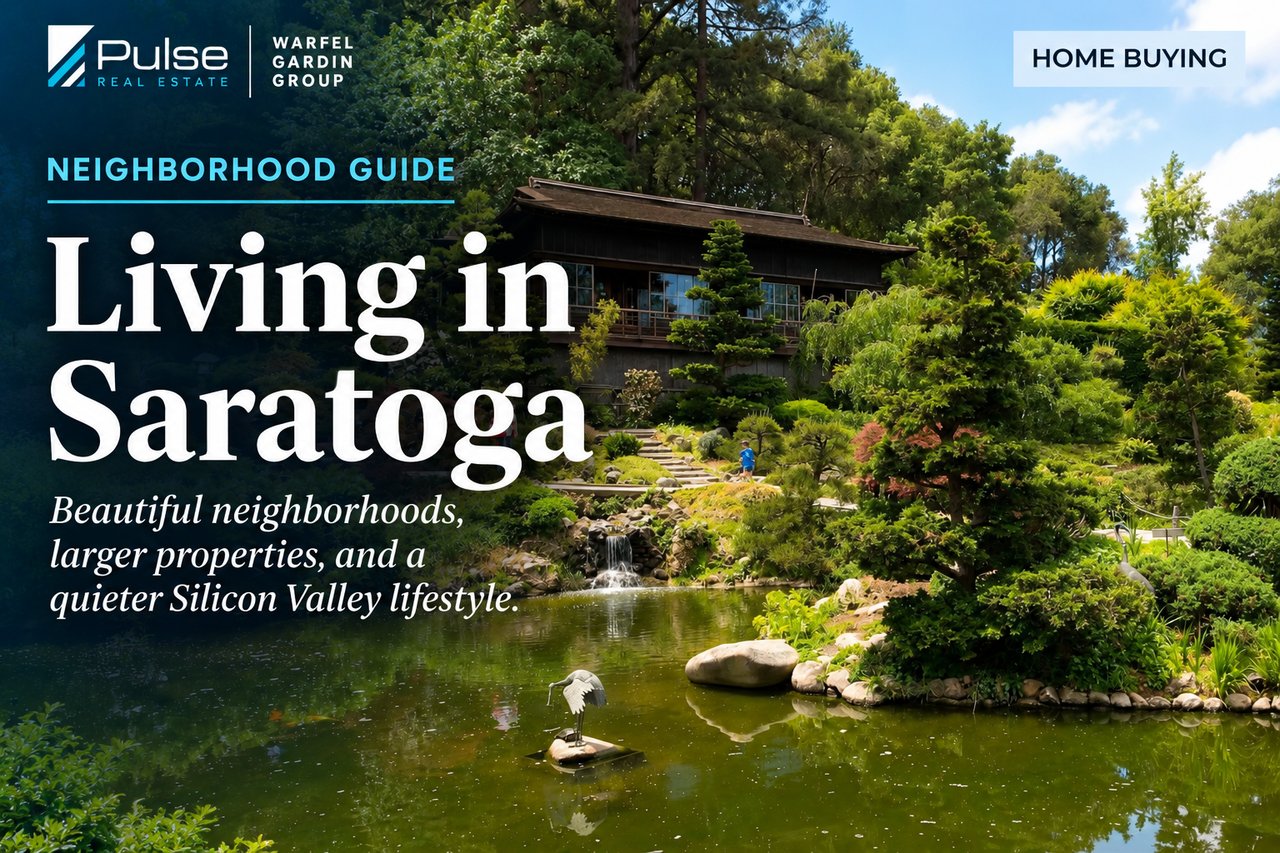
Larger properties, established neighborhoods, Saratoga Village, foothill living, and what buyers should know before choosing Saratoga
Home Buying
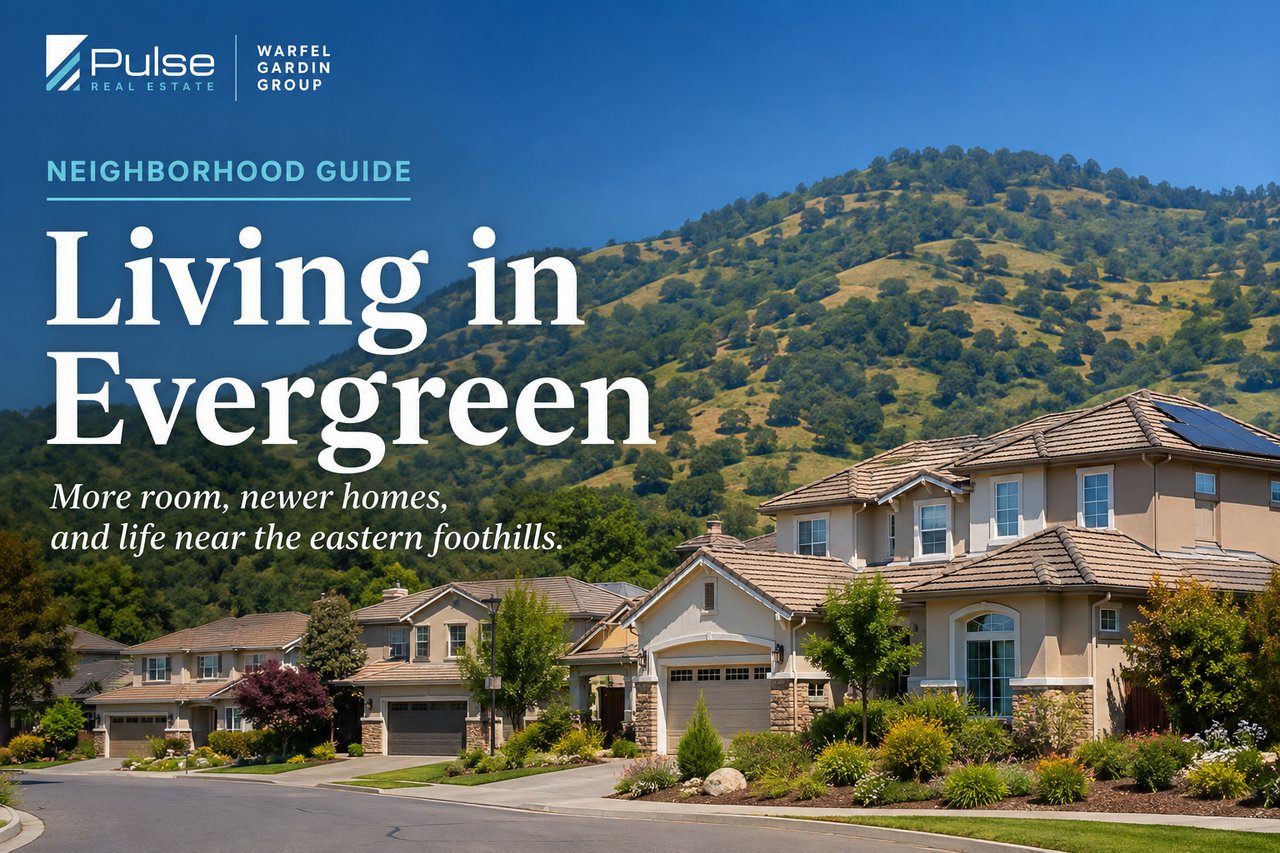
Foothill neighborhoods, more room to move up, and what buyers should know about life in East San Jose
Home Buying
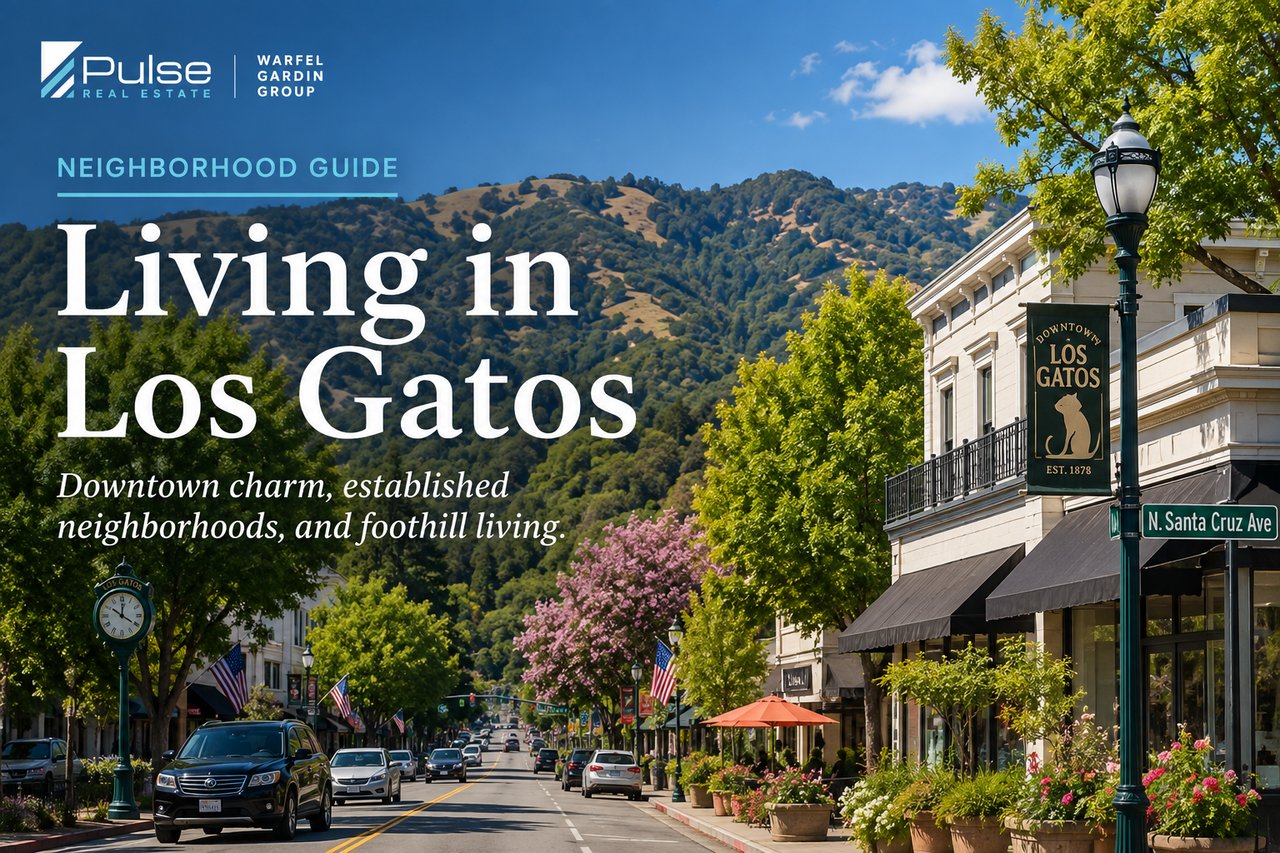
Downtown, established neighborhoods, foothill living, and what buyers should know before choosing Los Gatos
You’ve got questions and we can’t wait to answer them.